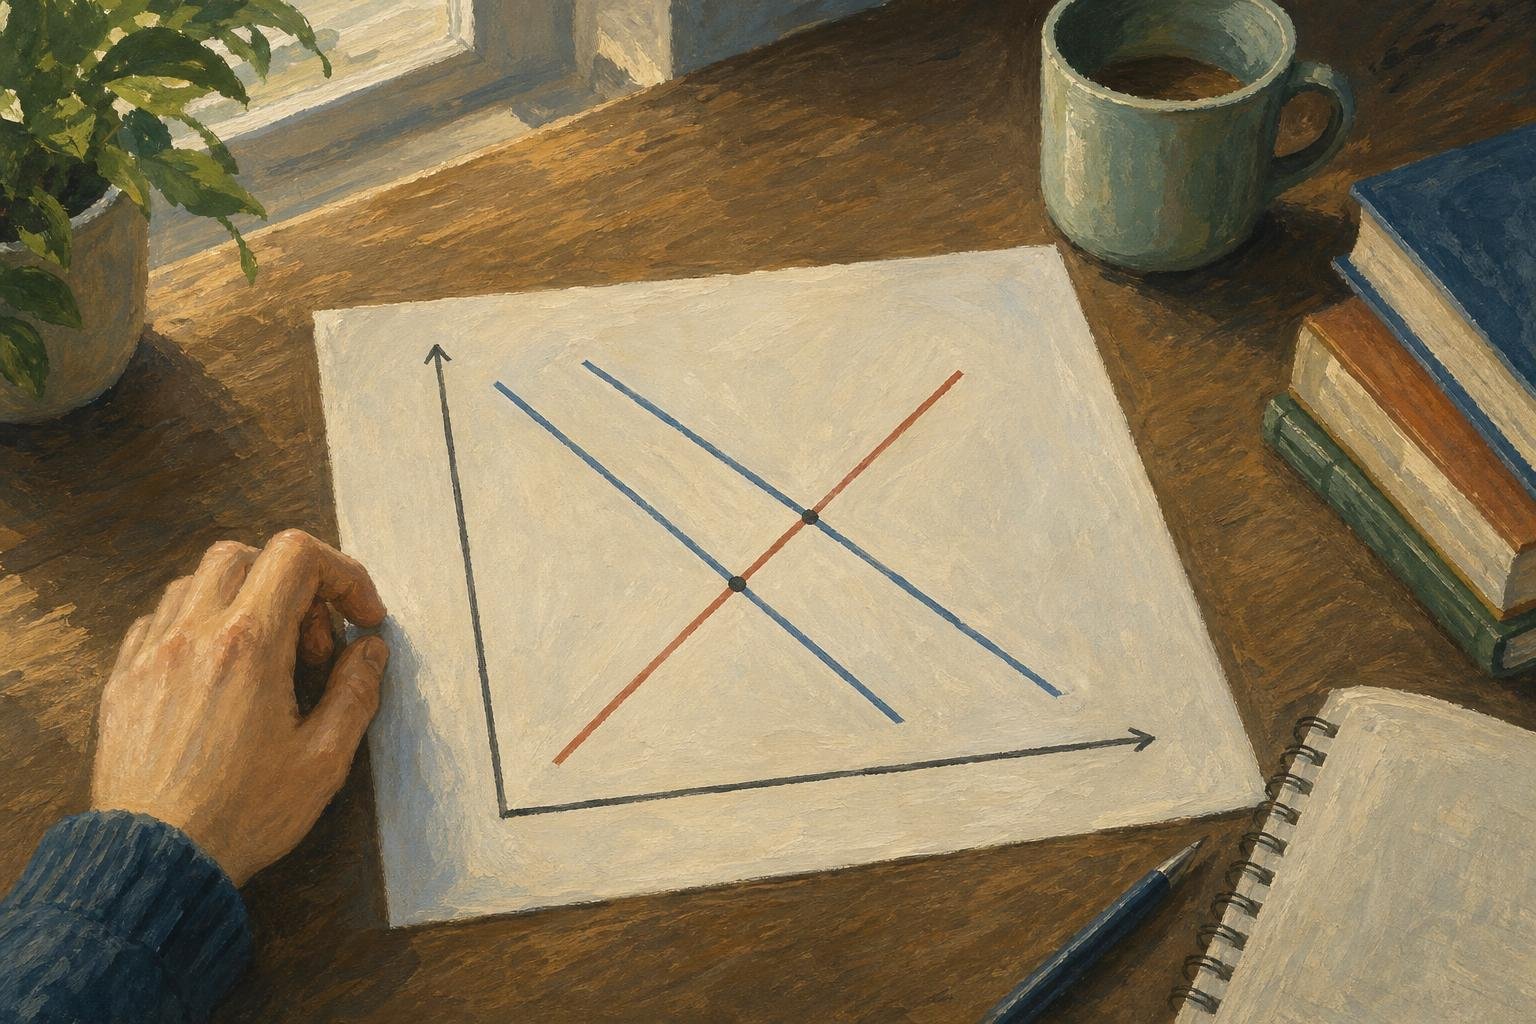

Suppose hotels cancel expansion plans, yet borrowing becomes cheaper. A loanable funds graph explains that apparent contradiction: weaker demand for investment financing can push interest rates down. The graph plots the real interest rate against the quantity of financing, showing where saving meets borrowing for investment.
Cheaper credit does not necessarily mean businesses are eager to grow. The reason rates change matters: more saving and weaker investment demand can both lower rates, but they send the quantity of financing in opposite directions.
In This Article
- What the Model Assumes
- Read the Axes and Find Equilibrium
- Separate a Movement From a Shift
- Work Through a Drop in Saving
- Work Through Weaker Investment Returns
- Handle Government Borrowing Consistently
- Key Takeaways
- Frequently Asked Questions
- Start With the Curve That Changes
What the Model Assumes
Consider a company issuing $10 million in bonds to buy equipment. Buyers of those bonds supply savings; the company uses the financing for investment. Households can also supply funds through bank deposits, with banks lending to businesses. The loanable funds market combines these channels into one market.
For the closed-economy version, imagine that the company’s financing comes entirely from domestic saving, with no international borrowing or lending elsewhere in the economy. That makes the connection direct: investment must be financed by national saving. The model groups borrowers with comparable risks together instead of assigning each company its own borrowing rate.
National saving includes private saving and government saving. In the simplified national-income framework, government saving equals tax revenue net of transfer payments minus government purchases. This combined saving supplies funds, while investment spending creates demand. The model studies their equilibrium real interest rate, not the central bank’s short-term policy rate. Government borrowing can also be drawn under a different convention, explained below.
Read the Axes and Find Equilibrium
Give the vertical axis a concrete value: suppose the equilibrium real interest rate is 4%. A nominal rate of 6% with expected inflation of 2% would produce approximately that real rate. The horizontal axis measures financing per period, such as dollars per year, rather than the accumulated stock of debt.
On a loanable funds graph, the horizontal position tells you how much financing changes hands. Label supply S and demand D; their intersection E gives the equilibrium rate and quantity, conventionally written r* and Q*.
Real interest rate, r
  ^
  | D       S
  |  \     /
  |   \   /
4%|----E---------
  |   /|\
  |  / | \
  +----|-----------------> Quantity of funds per year, Q
       Q*
Above the intersection, savers offer more funds than borrowers want, putting downward pressure on the rate. Below it, borrowers want more financing than savers offer, putting upward pressure on the rate. Those pressures resolve at E, where planned saving equals planned investment.
Separate a Movement From a Shift
Suppose a bakery shelves an expansion because its borrowing rate rises above the project’s expected return. Its appetite for financing has changed because financing became more expensive: that is a movement along the demand curve. The downward slope captures this response. Supply slopes upward because higher real returns encourage saving in the basic model; these are aggregate relationships, not identical responses from every saver or business.
Now change the bakery’s expected sales while keeping its borrowing rate fixed. If fewer customers make the expansion unattractive at that same rate, investment demand shifts left. A loanable funds curve shifts only when something other than its own interest rate changes desired saving or investment. Throughout the examples, follow the cause to the affected curve, then read the new intersection.
The table keeps the labels and comparisons together; the bakery example supplies the distinction behind them.
Loanable funds graph: what each feature tells you
| Graph feature or reading approach | Best for identifying | How to read it | Common reading error |
|---|---|---|---|
| Vertical axis: real interest rate (r) | The equilibrium price of borrowing | Read the rate at the intersection’s height; real rate ≈ nominal rate − expected inflation | Treating the axis as the nominal interest rate |
| Horizontal axis: quantity of loanable funds (Q) | The volume of saving and borrowing | Read the intersection’s horizontal position; use the stated currency and time period | Reading quantity as an interest-rate percentage |
| Upward-sloping supply curve (S) | Funds savers are willing to lend | At a specified real rate, read the quantity on S | Interpreting S as borrowers’ desired investment |
| Downward-sloping demand curve (D) | Funds borrowers want for investment | At a specified real rate, read the quantity on D | Interpreting D as demand for cash holdings |
| Intersection of S and D | Market-clearing rate and quantity | Project to both axes: r* is the real rate; Q* is funds supplied and demanded | Reporting the rate without the equilibrium quantity |
| Rate above or below equilibrium | Excess supply or excess demand | Above r*: Qs > Qd; below r*: Qd > Qs | Assuming any point on either curve clears the market |
| Two points on the same curve | A change in quantity supplied or demanded | Compare quantities at two real rates while keeping the curve fixed | Calling movement along a curve a supply or demand shift |
| Original and new intersections | The effect of a curve shift | Compare r₀ with r₁ and Q₀ with Q₁ after locating both intersections | Inferring the new equilibrium from the shifted curve alone |
A rightward supply shift, with demand fixed, lowers the rate and increases financing. A rightward demand shift, with supply fixed, raises both. When greater saving accompanies stronger investment demand, quantity increases, but the rate depends on which shift has the greater effect.
Work Through a Drop in Saving
Suppose a wave of unexpected car repairs makes households spend money they had intended to save. Their incomes have not changed, and neither has government saving. Repair bills now absorb part of the saving that would have helped finance business investment.
The supply of loanable funds shifts left, from S₀ to S₁: households supply less at every possible real interest rate. Investment demand stays at D. At the old rate, the available financing cannot cover what businesses want to borrow.
Competition for that smaller pool raises the rate. An equipment purchase that looked worthwhile at the old borrowing cost may no longer pay, so some businesses abandon projects. The new equilibrium E₁ sits above and to the left of E₀: a higher real rate, with less financing exchanged.
The abandoned projects do not represent a demand shift. They are the response to the higher rate along unchanged D. Saving fell first; investment contracted as financing became more expensive.
Work Through Weaker Investment Returns
Hotel investment offers a different starting point. The COVID-19 travel slump in 2020 provides a concrete setting for thinking about weaker expected returns. For a simplified example, suppose hotel operators expect fewer bookings and cancel plans for new rooms, while households’ willingness to save stays unchanged.
Those cancellations begin with the revenue outlook, not with an increase in borrowing costs. Even at the old rate, fewer hotel projects make financial sense. If that weakness reduces investment demand across the model’s combined market, demand shifts left from D₀ to D₁ against unchanged supply S.
Now lenders face fewer willing borrowers. The old rate leaves savings in excess of desired investment, so the rate falls. Savers respond to the lower return by supplying a smaller quantity along S, placing E₁ below and to the left of E₀.
Cheaper financing is the consequence of the retreat in investment demand. It does not erase the weaker revenue outlook that caused it. Compared with the repair-bill example, financing again contracts, but the rate moves the other way. Quantity alone cannot distinguish these shocks; the rate and the underlying event complete the explanation.
Handle Government Borrowing Consistently
A government deficit introduces a labeling choice before it introduces a curve shift. Under the national-saving convention used above, supply includes private and government saving, while demand represents private investment. Holding the private-saving schedule and investment-demand curve unchanged, a larger deficit reduces national saving at each real interest rate. National-saving supply shifts left, following the repair-bill example’s mechanics. The higher equilibrium rate then encourages more private saving along the unchanged private-saving schedule; it does not shift that schedule.
Some textbooks instead put private saving alone on the supply side. Their demand curve combines private investment borrowing with government borrowing. Under this convention, a larger deficit shifts total demand right, raising the equilibrium real rate and the total quantity exchanged, assuming upward-sloping supply.
That larger quantity includes government borrowing. Private investment still falls as the higher rate moves businesses along their own investment-demand curve. This reduction is called crowding out: government borrowing makes financing more expensive for private projects within the model.
Both conventions describe that pressure on private investment, but they count different quantities on the horizontal axis. Choose one. Shifting national-saving supply left and adding the same deficit to demand would count the fiscal change twice.
Key Takeaways
- Identify the event behind a rate change before interpreting it as good or bad news for investment.
- Read the equilibrium quantity as well as the rate; either alone can leave the cause unclear.
- Reserve “shift” for a change in saving or investment at a given rate.
- Define how government borrowing enters the graph before tracing crowding out.
Frequently Asked Questions
What is the loanable funds market?
The loanable funds market is a model connecting saving with borrowing for investment. A household’s bank deposit and a company’s equipment loan are examples of transactions it brings into one framework, even though they occur through separate accounts.
What shifts the demand curve for loanable funds?
Changes in expected investment profitability shift demand, as can government borrowing under the convention that includes it in demand. Stronger expected sales or business investment tax incentives can shift demand right; weaker expected returns shift it left. A hotel canceling new rooms because it expects fewer guests illustrates the latter.
Why is the demand curve for loanable funds downward sloping?
The demand curve slopes downward because higher real borrowing costs make fewer investment projects profitable. The bakery expansion illustrates a project dropping out as financing becomes more expensive. The supply curve has the opposite slope in this model.
Does a government deficit always shift the same curve in every textbook?
No: a deficit shifts national-saving supply left or shifts demand right when demand includes government borrowing. Look at whether the horizontal axis counts private investment financing or total borrowing, including government borrowing. That definition explains why the quantity predictions differ.
Is the interest rate on the graph nominal or real?
The graph uses the real interest rate, which adjusts the nominal rate for expected inflation. A quoted bank rate therefore needs that adjustment before it belongs on this axis. The adjustment lets you compare financing costs when inflation expectations change.
Start With the Curve That Changes
What matters is why financing becomes more or less attractive at a given rate. The supply and demand of loanable funds describe different decisions, even when their shifts move one outcome in the same direction.
The repair bills and canceled hotel expansions make the distinction concrete. Both leave less financing exchanged. Households saving less make funds scarcer, so the rate rises; businesses expecting weaker returns reduce competition for funds, so it falls. The useful diagnosis comes from connecting the rate to the quantity and the original change, not from reading the rate alone.
Recommended for you
Your Residual Plot: What a $5 Error Says About Fit
Use a residual plot to spot patterns in regression errors. Follow a lemonade stand's $5 error from calculation to model checks. See how to interpret the signs.
How to Find a Hobby That Truly Fits You
Give a hobby 21 days and 90 minutes per week, and you will learn more about your motivation, stress triggers, and attention than a dozen personality quizzes. A few concrete moves—testing a novel, a 5‑aside game, or a few low-stakes rounds of online gameplay—can reveal which activities calm your nervous system, sharpen focus, and actually […]
The Visual Language of Books: How Covers Communicate Complexity
At thumbnail size—often 100–160 pixels wide on retail grids—a cover must communicate genre, tone, and complexity before a reader can zoom in. The difference between a muddled thumbnail and a crisp focal point can determine whether a title gets a click, a pickup, or a pass. If you want a practical method for turning ideas […]
Reading a Linear Graph: Why the Slope Stays the Same
Understand a linear graph through constant slope, intercepts, and y = mx + b. Turn equations into points you can plot with confidence. See how it works.
Stem and Leaf Plot: Ordered Data, Every Value Visible
A stem and leaf plot keeps each value visible while sorting reading times into rows. Learn to build one, find the middle, and spot patterns. See how it works.
Box Plot Reading: A Shorter Box Doesn’t Mean Faster
A box plot shows center and spread, not speed alone. Use task-time examples to compare medians and variability on the same scale. See the worked example.
Dot Plot Explained: What Each Stacked Dot Tells You
A dot plot puts each observation above a number line. Learn how stacked dots show frequency and why equal spacing matters. See the study-time example.
Neural Network Diagram: Labels That Explain the Output
Read a neural network diagram without confusing scores with probabilities. Learn how arrows, layers, and activation labels clarify outputs. See the article.